 Enquire
Business Insurance
Building Insurance
Protect the Structure You Have Invested In
Protection for eligible structures — home, residential house, company premises, or factory — against covered risks, on a rebuilding-cost basis.
03
Cover options
29
Underwriters
24/7
Claims support
Quick overview
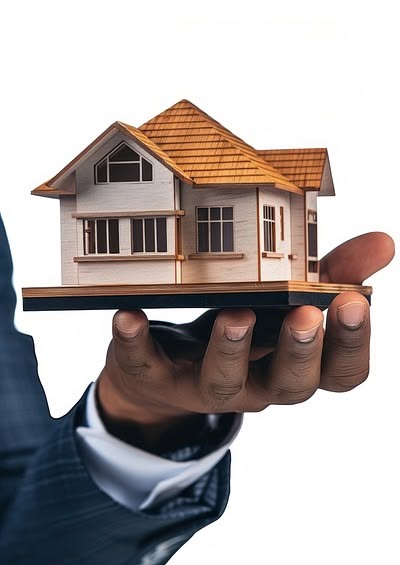
It covers the physical structure of a property — walls, roof, foundations, and permanent fixtures — against covered risks such as fire, storm, flood, and impact, on the basis of what it would cost to rebuild.
Why it matters
Why Building Insurance Matters
A serious event affecting your building can disrupt your home, business, tenants, or operations. Appropriate insurance helps reduce the financial burden of covered damage and supports recovery.
The structure is a major investment
Whether it is your home, a residential house, an office, commercial premises, or a factory, damage to the structure can result in significant rebuilding or repair costs.
Rebuilding your property
Depending on the policy, the sum insured can be based on the estimated cost of rebuilding the structure rather than simply its market value.
Who it's for
Who this cover is for
- Homes and residential houses
- Landlords of residential or commercial property
- Property investors and developers
- Companies that own their premises
- Factory and warehouse owners
Cover options
Your cover options
Choose the option that matches your needs. Exact terms, limits, and extensions vary by insurer and policy.
01
Structure & Fixtures
Covers walls, roof, floors, foundations, and permanent fixtures such as fitted kitchens, sanitaryware, and built-in wardrobes.
02
Insured Perils
Fire, lightning, explosion, storm, flood, impact by vehicles or falling objects, burst pipes, and malicious damage.
03
Fees & Clearance
Covers debris removal, architect and surveyor fees, and the cost of meeting current building regulations when rebuilding.
Protection
What this cover protects against
What applies to your policy depends on the cover level you choose and any extensions added.
local_fire_department
Fire & lightning
Damage from fire, lightning, and explosion.
storm
Storm & flood
Weather damage to the structure.
car_crash
Impact
Damage from vehicles, falling objects, or aircraft.
water_damage
Burst pipes
Escape of water from plumbing and tanks within the building.
engineering
Debris removal & fees
Clearing the site, plus architect and surveyor fees for the rebuild.
Key benefits
What you get with the cover
Rebuilding-cost basis
Cover is set on what it would cost to rebuild, not the market or resale value.
Residential or commercial
One product for homes, rental blocks, offices, warehouses, and factories.
Lender-friendly
Meets the building-insurance condition attached to most mortgages and property loans.
Professional fees included
Architect, surveyor, and regulatory costs of a rebuild are covered alongside the works.
Exclusions
What's not covered
Wear and tear, and gradual deterioration
Existing structural defects and subsidence (unless specifically covered)
Land value
Property left unoccupied beyond the policy limit
Faulty workmanship and design
This is a general list. Your policy wording sets out the full exclusions that apply.
Getting covered
What you'll need
To take out cover
- Copy of ID or company registration documents
- Property ownership / details
- Property location
- Building description
- Estimated rebuilding value
- Property valuation where required
- Details of existing insurance, if applicable
Make the property safe, prevent further damage, take photographs, and notify Cush immediately so a loss adjuster can be appointed and the rebuild can start.
Requirements may vary depending on the insurer, type of cover, risk involved, and individual circumstances. Our team will advise you on the specific documents required for your policy.
Glossary
Common terms explained
Reinstatement Value
The full cost of rebuilding the property as new, including fees and debris removal — the correct basis for the sum insured.
Underinsurance
Insuring for less than the full rebuilding cost, which lets the insurer reduce claim payments proportionately.
FAQ
Frequently asked questions.
The essentials on building insurance — what it covers, what you'll need, and how claims work. More on the FAQ page.
See all FAQsShould I insure for the market value or the rebuilding cost?
Always the rebuilding cost. Market value includes land and location; a claim is settled on what it costs to rebuild the structure.
Does it cover the contents too?
No — building cover is the structure and permanent fixtures. Contents are insured separately, or together under a home or domestic package.
Is building insurance required for a mortgage?
Almost always. Lenders require the building to be insured for its full reinstatement value for the life of the loan.
Flexible cover
Set on the rebuilding cost
We help you set the sum insured on a proper rebuilding-cost basis so you're not caught by underinsurance. Protect the structure that protects your investment with Cush Insurance Agency.
More Business Insurance Enquire  Enquire
 Enquire
Related cover
Enquire Enquire Business Insurance
Goods in Transit (GIT)
Protect Your Goods While They Are on the Move
Enquire Business Insurance
Workplace Injury Cover (WIBA)
Protect Your Employees. Protect Your Business.